Gentex Corporation (Nasdaq: GNTX), a leading auto parts supplier and owner of Voxx Int’l and its Klipsch, Onkyo, and Integra brands, reported results for the third quarter of Fiscal 2026. The company revealed it is facing continued headwinds in Fiscal 2026, including a China business hit hard by international trade instability and tariffs, rising parts & component costs (particularly precious metals), and a softening U.S. auto market. It also noted that it has lost a program with Volkswagen, which directly impacts revenues.
But the company also took advantage of its mixed results to make the point that its decision to diversify its business through the addition of various technology investments, including Voxx International with its Premium Audio Company division, helped to soften the blow of the global instability it continues to face.
Learn all about Gentex’s Fiscal 2026 Q3 results…
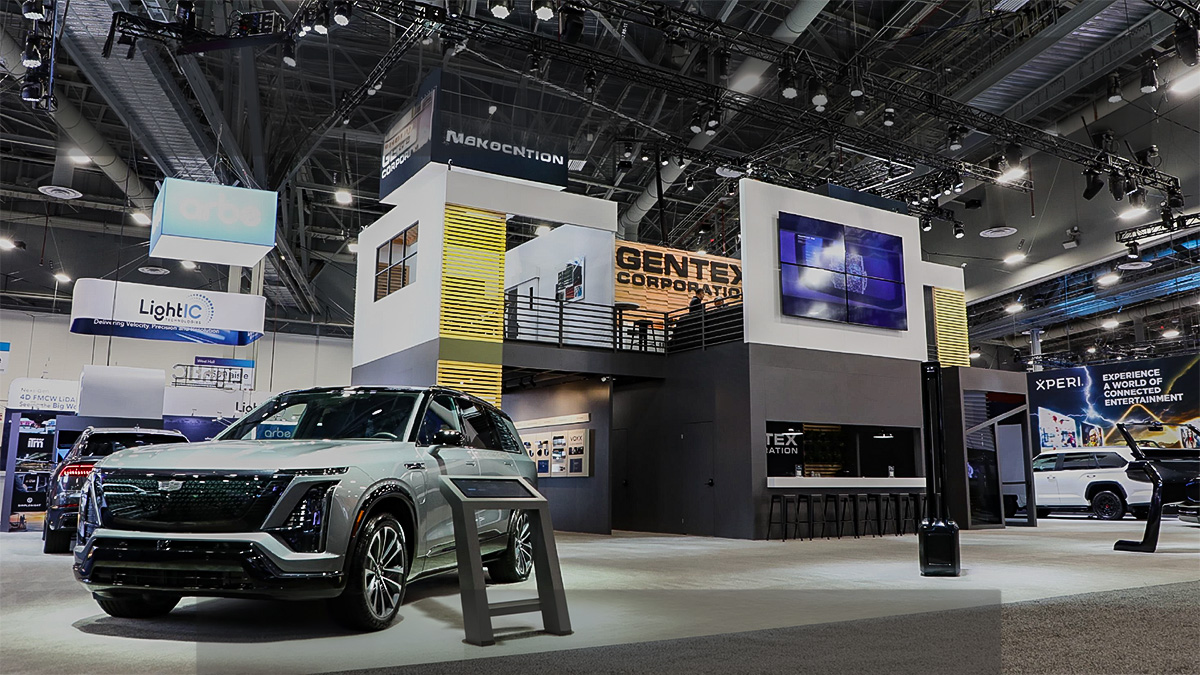
Based in Zeeland, Michigan, Gentex has, for many years, been an important supplier to the automobile industry based in Detroit, MI. While it offers several products for installation in vehicles, its most important product category is interior and exterior mirrors. In April last year – the beginning of the second quarter of Fiscal 2025- the company closed on its proposed acquisition of Voxx International, in an effort to further diversify its business base.
An Automotive Electronics-Adjacent Business to Augment Its Own
In the mind of the executive team at Gentex, Voxx offered a unique opportunity. Like them, Voxx was substantially a supplier of automotive-related products. However, while it was clearly automotive-industry adjacent, it had a different structure and approach. For example, it had a large and healthy distribution business. In addition to that, Voxx had also acquired several mobile electronic brands that helped to augment its distribution business by taking it into manufacturing.
Finally, Voxx had also made a concerted effort to diversify its business via an entry into more consumer electronics products – especially loudspeakers and audio electronics under well-known brands such as Klipsch, Onkyo, and Integra. With this one acquisition, Gentex saw an opportunity to further expand its auto parts business, while also diversifying into consumer electronics.
So as CEO Steve Downing began sharing some of the more troublesome numbers resulting in the third quarter of Fiscal 2026, he was only too happy to point out the offsetting positive results of both Voxx’s Premium Audio Company results, as well as some of their own internal divisions in which they sought to diversify beyond just the automotive parts business.
Fiscal 2026 Revenues Struggled Again in Q3
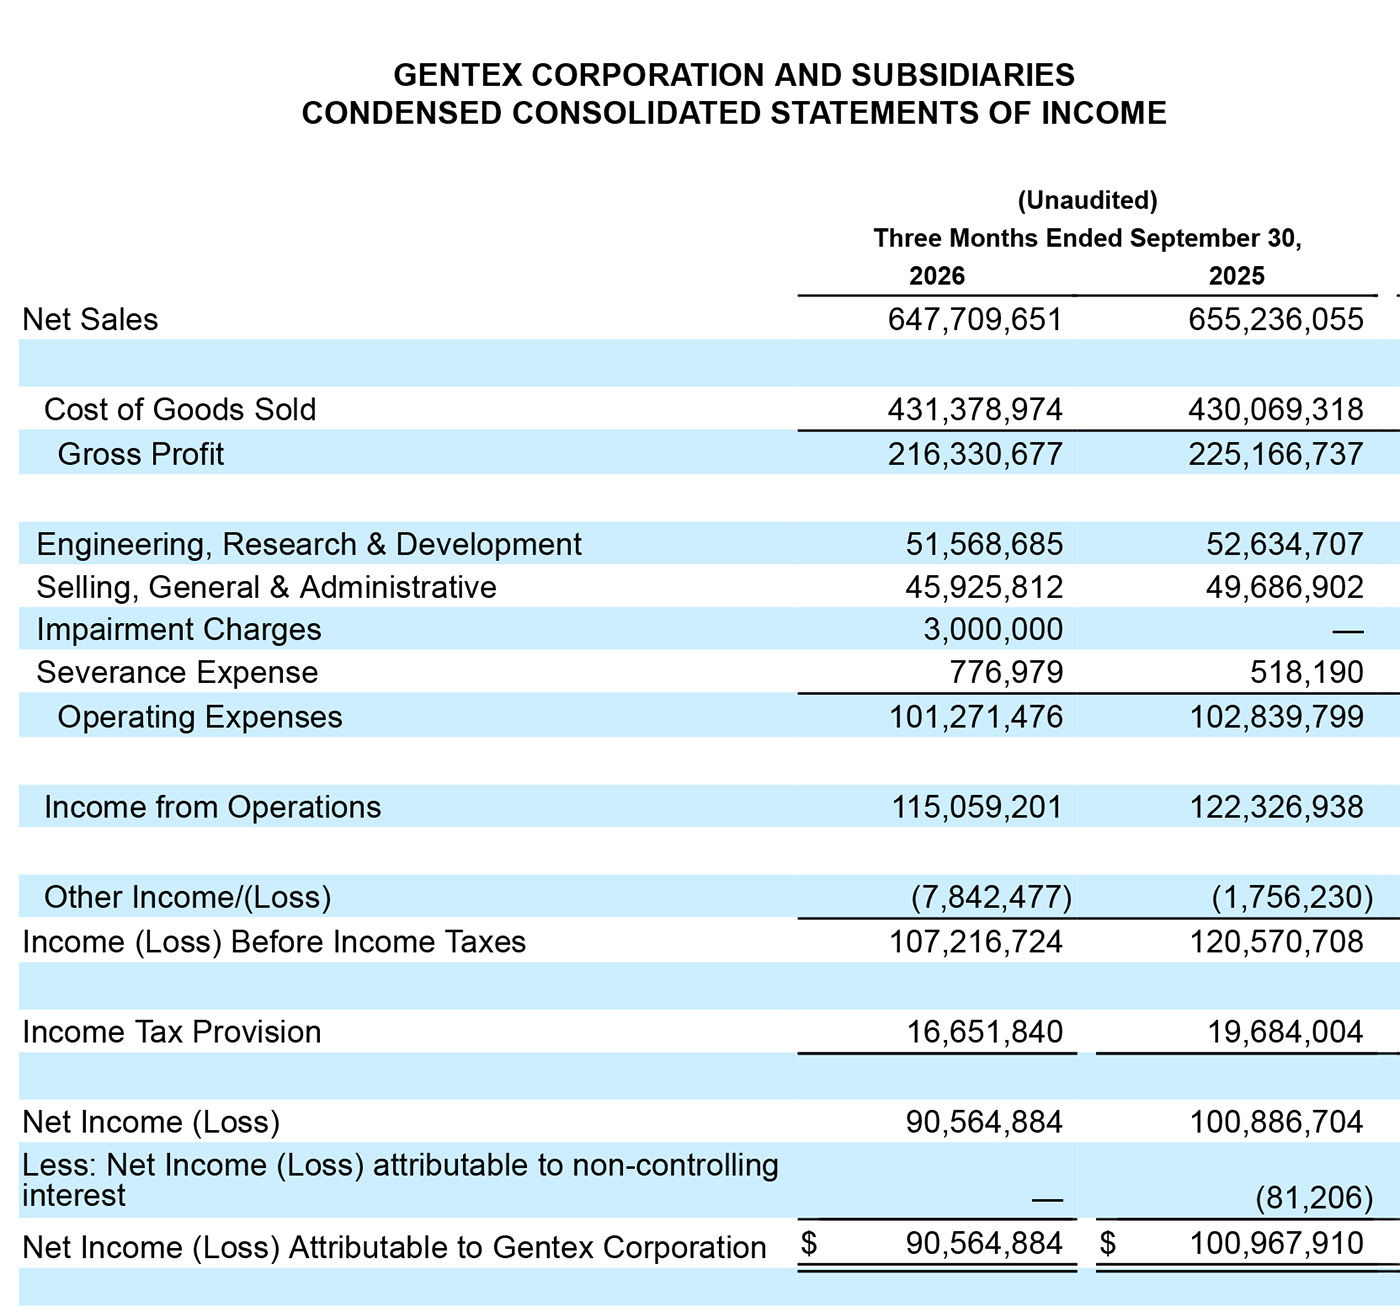
Overall net sales in the third quarter came in at $647.7 million, down $7.5 million or -1.2% from the net sales of $655.2 million in the same quarter last year. This was the second consecutive quarter with a decline in net sales versus prior year results. In Q2, net sales dropped $6.6 million or about -1% compared to Q2 in Fiscal 2025.
But worse than that, the third quarter result was down by about $35 million compared to the forecast the company had provided at the beginning of the quarter. The reason for that more more substantial decline?
“Automotive unit performance was generally in line with our expectations, but revenue came in approximately $35 million below our beginning-of-quarter forecast due to certain customer issues and delayed launches,” Gentex CEO Steve Downing told analysts on a conference call to discuss the quarterly performance.
A Better-Than-Industry Result Offset by the Loss of a Volkswagen Program
Downing was quick to point out that in North America, Gentex’s automotive revenue increased approximately 3% “…despite a 5% decline in regional light vehicle production.” He also told analysts that in Europe, its automotive division actually had a revenue increase of 13%…IF YOU EXCLUDE the loss of the Volkswagen program. The loss of that program, however, completely wiped out the revenue gain for all of Europe in the quarter.
Gentex’s prepared announcement made that same point in relation to its global revenue performance. While industy data showed that global light vehicle production declined by more than 2% year-over-year in the quarter, Gentex beat that result. Saying, “Globally, automotive revenue performance achieved a 2% year-over-year growth apart from the previously announced headwinds in China and with VW.” [Emphasis added]
Premium Audio Co and ‘Other Products’ Division Add Positive Pressure
While those excuses might be debatable, what’s not up for debate is that the company had two divisions that contributed solid growth that helped to offset those other declines (or, as they like to put it, headwinds). One of those better-performing divisions was Premium Audio Company, and the other was the division it calls “Other Products.”
Premium Audio Company, the division that is home to popular consumer audio brands like Klipsch loudspeakers, Onkyo electronics, and Integra electronics, “grew meaningfully,” the company said. With quarterly revenues coming in at $54.7 million, PAC revenues grew by $11 million or 27%, higher than revenues of $43.0 million in the same quarter last year.
The company said that PAC’s growth mostly came from higher sales of home separates and systems products. It defined home separates as Reference Premiere speakers, and systems products growth as coming from Flexus, the second generation of the Fives, Sevens, and Nines, and ProMedia products. These are mostly speaker products.
PAC and ‘Other Products’ Generate About 15% of Total Revenues
Other Products is a division that includes Aerospace, Biometrics, Fire Protection, and Automotive Aftermarket. In many cases, this Other Products division represents technology investments made by the company over the last few years, seeking to further diversify its business. In the third quarter, Other Products’ collective revenue grew to $40.5 million, or by 4.9% compared to the same quarter in Fiscal 2025, with $38.6 million in combined net sales.
Downing told analysts that global non-automotive revenues overall increased “approximately 17% year over year” and now represent about 15% of total company revenue in the third quarter. Last year, non-automotive revenue in the quarter represented about 12% of total revenue. Still, there’s no denying that the company’s automotive division remains the lion’s share of its business.
How Did Profits Perform Compared to Revenues?
The company reported that third-quarter gross margin came in at 33.4%. That is down 100 basis points, or a full 1% from a gross margin of 34.4% in the third quarter of Fiscal 2025. Why the margin compression? Gentex’s CEO Downing told analysts that this drop in gross margin was largely due to higher precious metal costs and the impact of lower-than-anticipated sales, “which resulted in unfavorable product mix and reduced operating leverage during the quarter.”
Downing noted that the higher precious metal costs “[have] been an ongoing headwind over the last few quarters as these commodity prices have increased significantly.” These increased costs, combined with the sales shortfall, hurt leverage and results, but Downing expressed confidence in the company’s ability to “engineer solutions to help offset the inflationary cost environment that exists in a number of different commodity areas.”
Analysts Concerned About Ability to Control Inflationary Risks
Perhaps unsurprisingly, when the presentation opened the floor to questions from analysts, several of them zeroed in on the issue of cost control in a continuing inflationary climate. Of particular interest, which is of course industry-wide, several analysts questioned the company executives about the impact of memory chips, processors, and other material costs.
At least one analyst pointed out that this was the second quarter in a row with a combination of revenue declines and increasing costs. Gentex execs did their best to assure analysts they were on top of the situation.
The company reported $1.5 million drop in Operating Expenses, largely as a result of serious belt-tightening in Engineering, Research & Development expenses (down about $1.1 million), as well as in Selling, General & Administrative expenses (down about $3.7 million). But these gains were more than offset due to a $3.0 million impairment charge and another $777 thousand severance expense charge.
Income from Operations, aka Operating Profits, Drop 6%
As a result of this, Income from Operations dropped to $115.1 million, a decline of $7.3 million or 6% compared to the income from operations of $122.3 million in the same quarter last year.
In another noteworthy development, Gentex reported a Total Other Loss of $7.8 million in Q3. This caught my eye as it was a substantially larger loss – $6 million greater – than the same quarter in Fiscal 2025 of $1.8 million. What was this loss attributed to? “The year-over-year change [in Other Income/(Loss)] primarily reflects certain credit loss reserves and investment-related charges, partially offset by higher investment income and gains on asset and investment sales.”
Loss of Leverage Led to Double-Digit Drop in Net Income
These added charges against earnings, combined with lower-than-anticipated net sales, caused a loss of leverage and resulted in a meaningful drop in Net Income. For the quarter this year, Gentex reported a net income of $90.6 million. That was a decline of $10.3 million or 10.2%, as compared to a net income of $100.9 million in the third quarter of last year.
Based on having completed a full nine months of the current fiscal year, Gentex chose to address its guidance – its forward estimate of expected performance for full year 2026. It also reiterated its preliminary full-year guidance for Fiscal 2027. The company had previously offered a revenue guidance for Fiscal 2027 of $2.8 billion-to-$2.9 billion…a better-than-5 % rate of growth. The company has reiterated this forecast for 2027.
2026 Annual Guidance is Revised Downwards While 2027 is Reiterated
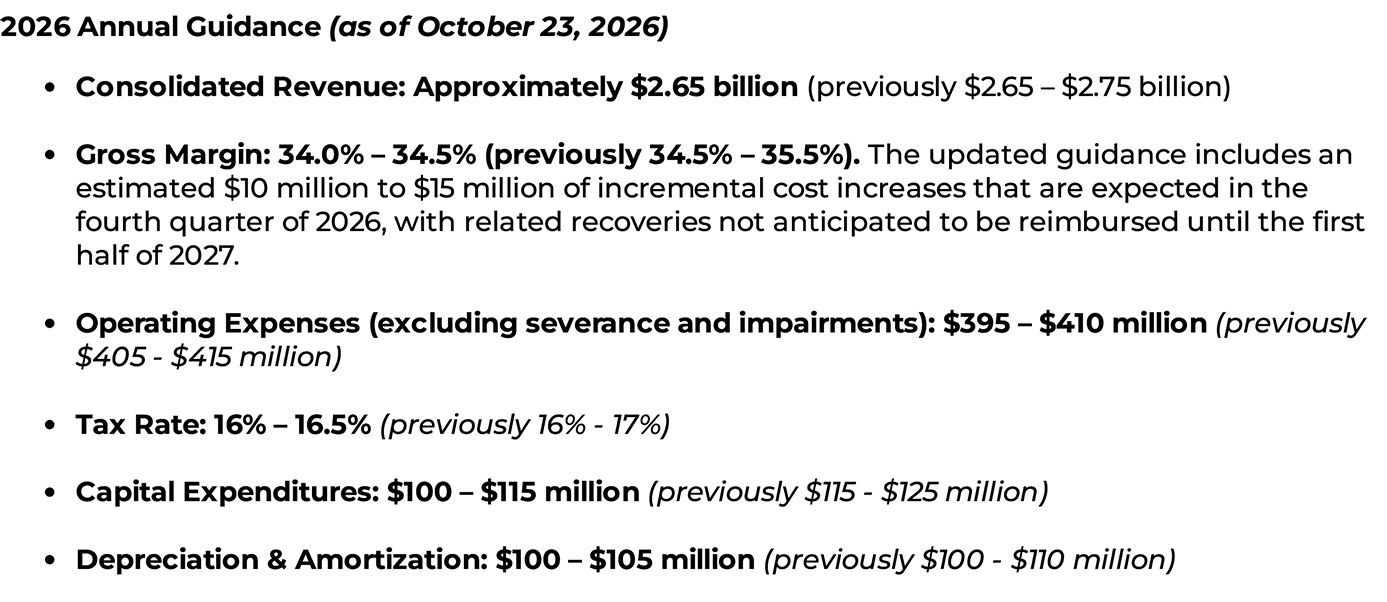
But the company chose to issue a downward revision for the remainder of Fiscal 2026, based on current trends. The revisions were as follows (with my comments added).
- Consolidated Annual Revenue: Revised to approximately $2.65 billion. [Current 9-Month revenue: $1.97 billion…Last year’s revenue: $2.5 billion] Previously, the company offered analysts a forecast of $2.65-$2.75 billion. When companies offer a range like this, analysts peg the midpoint number as what they are looking for. So, in other words, analysts looked at that previous guidance and set their expectation at $2.7 billion. So this is a downgrade by the company.
- Gross Margin: Now set at 34.0% – 34.5% (Previously set at 34.5% – 35.5%). Another downgrade, as analysts were likely expecting a GM of 35% based on the previous forecast. Now, they will expect the lower 34.25%
The company offered forecasts on other line items, such as operating expenses, tax rate, capital expenditures, and more. But the key items above look to be the most impactful on analysts’ feelings about the company.
What Did Wall Street Think?
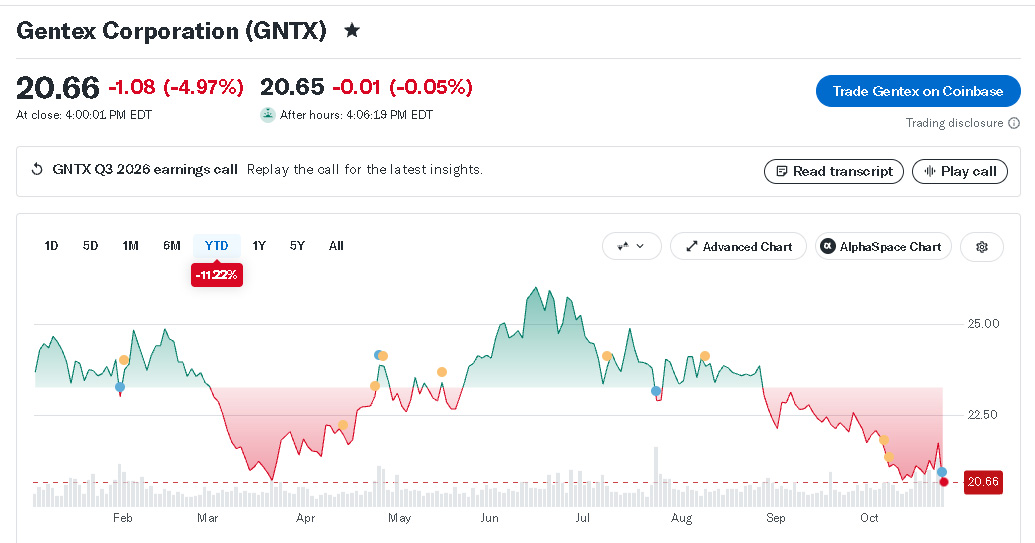
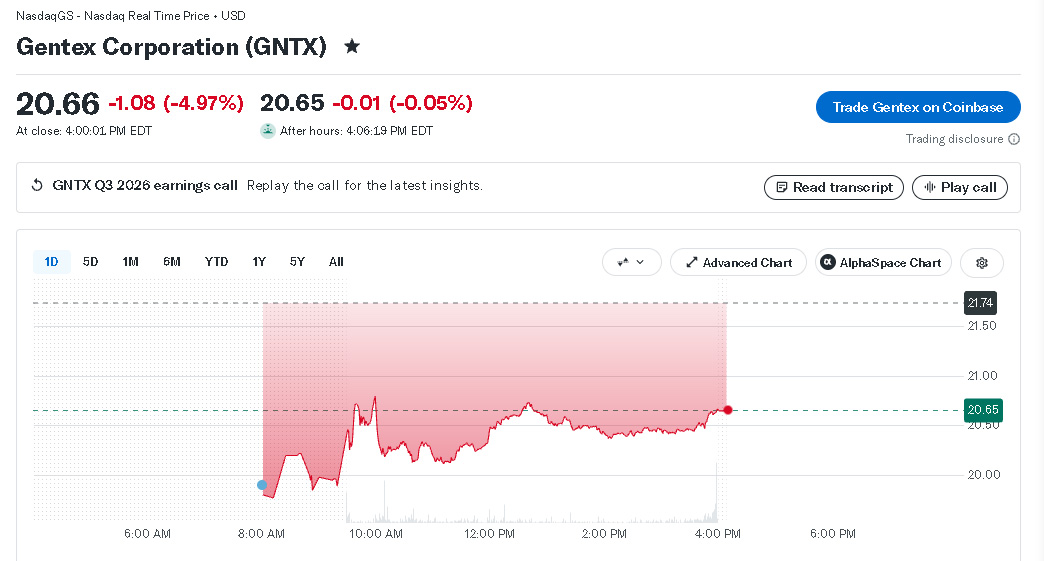
How did Wall Street react to the earnings report from Gentex? Not well. The company released its third-quarter results on Friday, October 23rd, before the market opening, with an earnings conference call scheduled at 9:30 a.m. By the end of trading, the value of Gentex shares had dropped 5%, closing at $20.66 per share. After-hours trading continued to show a downward trend. At times during the day, shares traded as low as $19.98.
Learn more about Gentex by visiting gentex.com.


Leave a Reply